Cheapest Car Insurance for Seniors Over 70 — Vermont
Free to compare
Why Your Defensive Driving Certificate Didn't Lower Your Premium
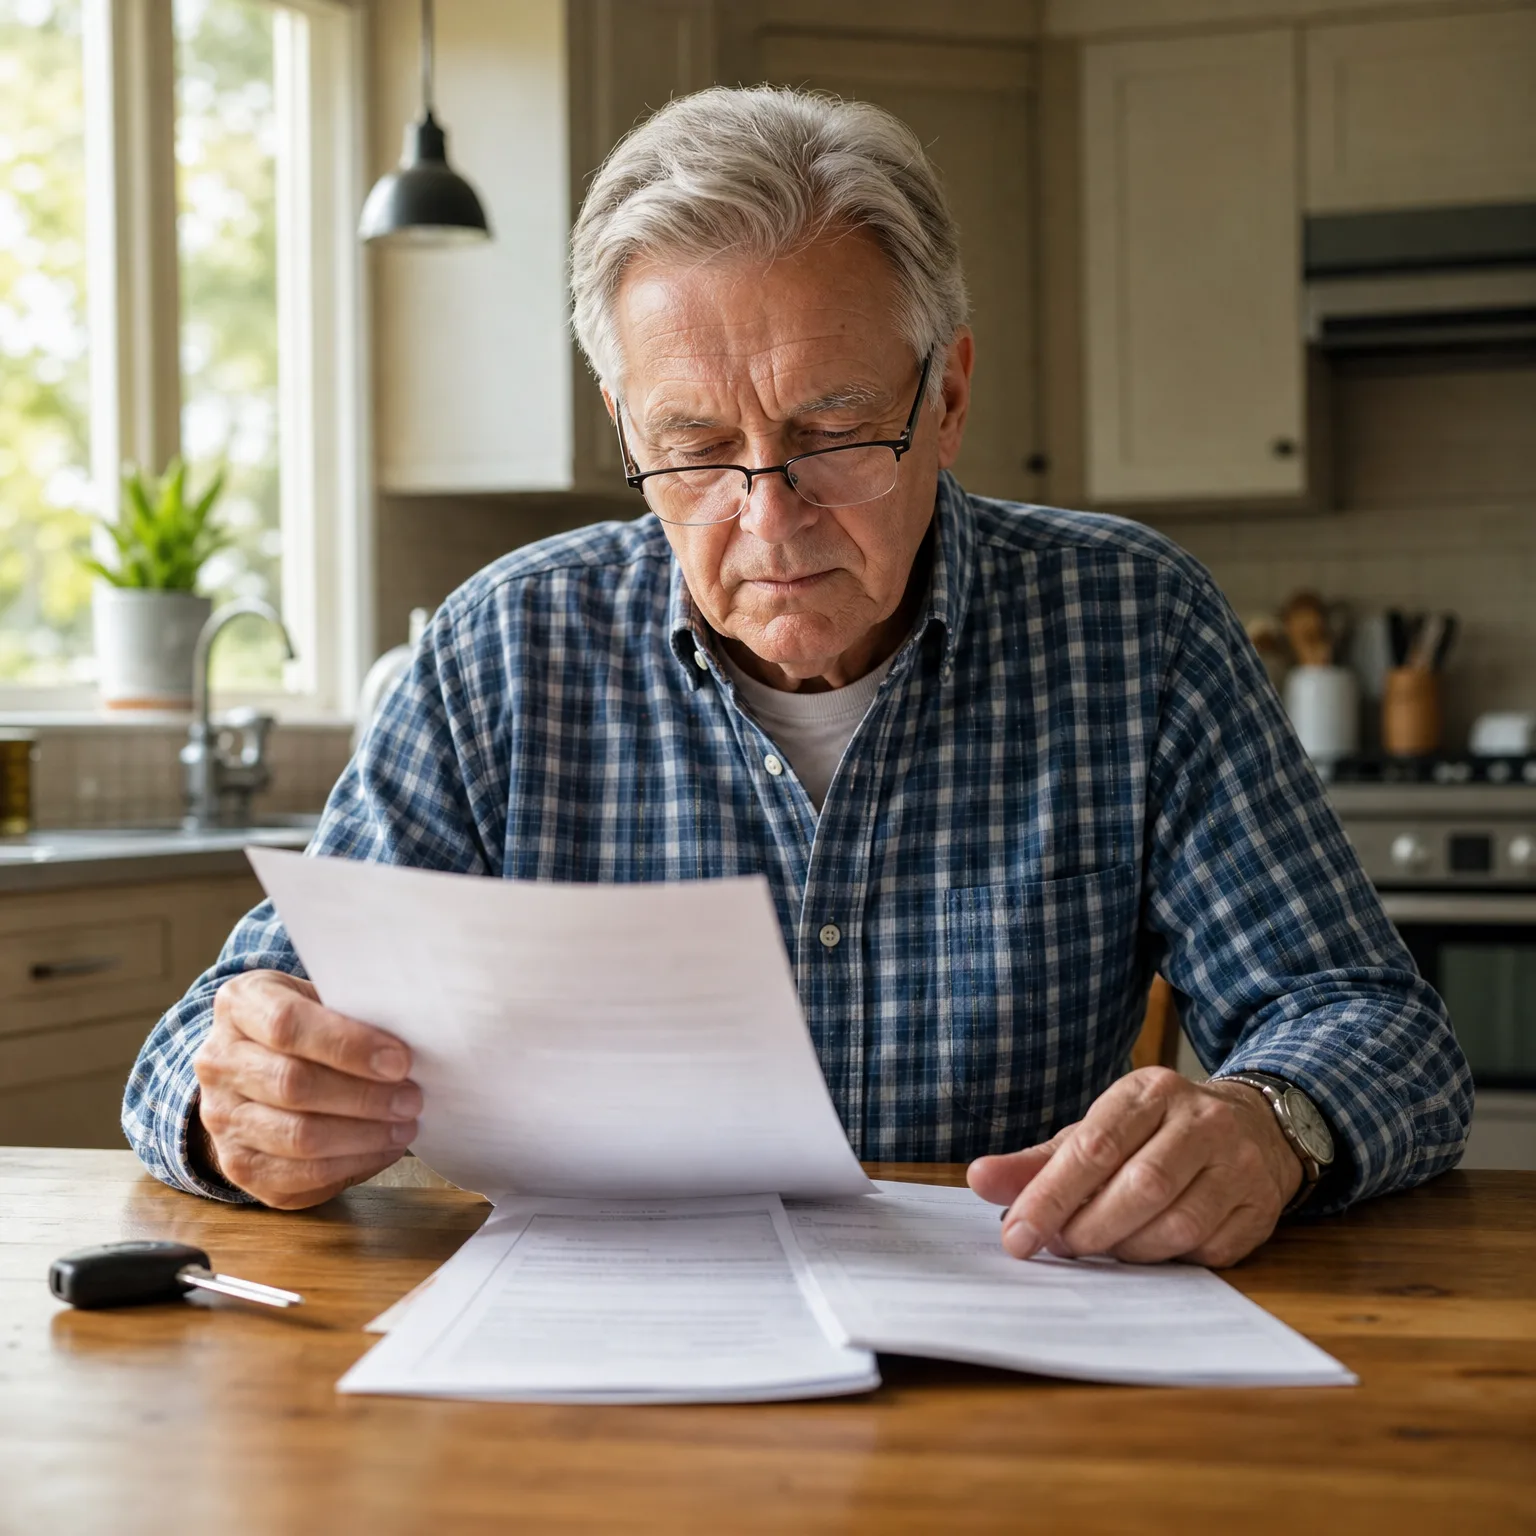
You completed the defensive driving course your neighbor recommended. You mailed the certificate to your agent three months before renewal. Your new premium arrived at the same rate as last year, with no mention of a discount. You called the agent, who said the discount was already applied. The math doesn't add up, and you're not sure what just happened.
Vermont does not require insurers to offer a mature driver discount. When a carrier does offer one, the amount is set by that carrier's own filing with the state Department of Insurance. Most carriers will not apply the discount automatically at renewal even when you've completed an approved course. The certificate proves eligibility, but the discount requires a separate request in most cases. If your agent never filed the request or the carrier's system never flagged your policy for review, the discount never attached.
“The course proves you're eligible; it does not trigger the discount unless someone manually applies it.”
Find Coverage Made for Drivers Over 65
Get My Senior Auto Insurance Quote$25,000
Vermont Bodily Injury Minimum Per Person
Vermont's minimum liability is $25,000 per person, $50,000 per accident, $10,000 property damage. Seniors with retirement assets often carry higher limits because the minimum exposes everything above it in an at-fault accident.
23 V.S.A. § 800 et seq.
The Structural Reality: No Mandate Means No Guarantee
Vermont law does not mandate a senior or mature driver discount. Carriers may offer one voluntarily, and many do, but the percentage varies by carrier and is not published in rate filings accessible to the public. The only way to know what a carrier's discount is: ask them directly and request it be applied to your policy.
This creates a structural gap. You can complete an approved defensive driving course, submit the certificate, and still pay the higher rate indefinitely if the carrier's system never flags your policy for the discount. The course proves you're eligible. It does not trigger the discount unless someone at the carrier or agency manually applies it.
The course-completion certificate typically expires after three years. If the discount was never applied in the first place, you've now paid the higher rate for three years and the certificate is no longer valid. You would need to retake the course to requalify. The carrier will not notify you that the certificate expired or that the discount was never applied.
The blocker: you lack confirmation that the discount was applied and you lack the carrier's stated discount percentage to verify the math yourself.
Related Articles

Cheapest Car Insurance for Seniors Over 70
7/4/2026
Best Car Insurance for Seniors Over 70 VT
7/5/2026
Cheapest Car Insurance for Seniors Over 70 NH
7/4/2026
Cheapest Car Insurance Seniors 70+ Virginia
7/4/2026
Cheapest Car Insurance for Seniors Over 70 KY
7/4/2026
Cheapest Car Insurance Seniors 70+ Montana
7/4/2026
Which Carriers Write in Vermont and What You Can Expect
Fifteen major carriers write auto insurance in Vermont. Standard-tier carriers include State Farm, Geico, Progressive, Allstate, Travelers, Nationwide, Liberty Mutual, Farmers, and Hartford. Preferred-tier carriers include USAA and Amica. Non-standard carriers include Dairyland and The General. National General writes in the standard tier with some non-standard programs.
State Farm, Geico, Progressive, USAA, Dairyland, National General, and The General all offer online quotes. Most standard and preferred carriers offer mature driver discounts, but the percentage is set by each carrier's own filing. You will not see the percentage on the carrier's website. You must request a quote and ask the agent or representative what the mature driver discount percentage is for your policy.
Low-mileage programs are available from most standard carriers. If you no longer commute and drive fewer than 7,500 miles per year, ask each carrier whether they offer a low-mileage discount and what documentation they require to verify annual mileage. Some carriers use telematics devices; others accept an odometer photo at renewal.
15
Major Carriers Writing in Vermont
Fifteen carriers write auto insurance in Vermont across standard, preferred, and non-standard tiers. Comparing at least three carriers gives you visibility into how each prices your profile and what discounts each applies without requiring a request.
Vermont Department of Financial Regulation licensure records
The Coverage Decision: Full Coverage on a Paid-Off Vehicle
If your vehicle is paid off and worth less than a conventional threshold, dropping collision and comprehensive coverage may make sense. The conventional rule of thumb: if the vehicle's current market value is less than ten times your annual collision and comprehensive premium, the coverage may cost more over time than the vehicle is worth.
Run the math with your own figures. Log into your carrier's portal or call your agent and ask: what is my current annual premium for collision coverage alone, and what is my current annual premium for comprehensive coverage alone. Look up your vehicle's current market value on a valuation site. Multiply your combined collision and comprehensive annual premium by ten. If that number exceeds your vehicle's market value, you are paying more in coverage over ten years than the vehicle is worth today.
Dropping collision and comprehensive does not affect your liability coverage, which protects your retirement assets in an at-fault accident. Vermont requires uninsured motorist coverage, which remains in place regardless of whether you carry collision or comprehensive. Medical payments coverage and personal injury protection are optional in Vermont; if you have Medicare, ask your agent whether med pay duplicates your Medicare coverage or fills a gap.
What to Do Right Now
Request a copy of your current policy declaration and confirm whether the mature driver discount appears as a line item. If it does not, call your carrier and ask what documentation they need to apply it. If you completed a defensive driving course more than three years ago, the certificate has likely expired and you will need to retake the course.
Request quotes from at least three carriers writing in Vermont. Ask each carrier what their mature driver discount percentage is, whether they offer a low-mileage program, and what the annual premium would be with both discounts applied. Write down each carrier's answers and compare the final annual premium, not just the discount percentages.
If your vehicle is paid off, ask each carrier for a quote with liability and uninsured motorist coverage only, and a separate quote with collision and comprehensive added. Compare the annual premium difference against your vehicle's current market value. Make the coverage decision based on your own asset exposure, not on what the agent recommends.
How to Confirm the Discount Was Applied
Request a copy of your current policy declaration from your agent or log into your carrier's online portal. Look for a line item labeled mature driver discount, defensive driving discount, or senior discount. If the line item appears, note the dollar amount or percentage. If it does not appear, the discount was not applied regardless of what the agent told you over the phone.
Call the carrier directly and ask: what is your mature driver discount percentage for Vermont policies, does my policy currently have it applied, and what documentation do you need from me to apply it if it is missing. Write down the representative's name, the date, and their answers. If they say the discount is already applied but you see no line item on the declaration, ask them to email you a breakdown showing where it appears.
Get Your Free Quote
Get My Senior Auto Insurance QuoteFrequently Asked Questions
Does Vermont require car insurance companies to offer a senior discount?
No. Vermont does not mandate a senior or mature driver discount. Carriers may offer one voluntarily, and many do, but the percentage is set by each carrier's own filing with the state. Ask each carrier what their discount percentage is and whether it has been applied to your policy.
How do I know if my mature driver discount was actually applied?
Check your policy declaration for a line item labeled mature driver discount, defensive driving discount, or senior discount. If the line item does not appear, the discount was not applied. Call your carrier and ask them to confirm whether the discount is on your policy and what documentation they need to apply it.
How long does a defensive driving course certificate last in Vermont?
Most carriers accept defensive driving certificates for three years from the completion date. After three years, the certificate expires and you must retake the course to requalify for the discount. The carrier will not notify you when the certificate expires.
Should I drop collision coverage on my paid-off car?
Run the math with your own figures. If your vehicle's current market value is less than ten times your annual collision and comprehensive premium, the coverage may cost more over time than the vehicle is worth. Dropping collision does not affect your liability coverage or uninsured motorist coverage.
Which car insurance companies in Vermont offer the best rates for seniors over 70?
Rates vary by driving history, vehicle, and location. State Farm, Geico, Progressive, USAA, and Amica all write in Vermont and offer mature driver discounts, but the percentage is set by each carrier. Request quotes from at least three carriers and compare the final annual premium with all applicable discounts.
Do I need medical payments coverage if I have Medicare?
Medical payments coverage and personal injury protection are optional in Vermont. Medicare covers most medical expenses after an accident, but med pay may cover deductibles, copays, or expenses Medicare does not cover. Ask your agent whether med pay duplicates your Medicare coverage or fills a gap.