Cheapest Car Insurance for Seniors — Massachusetts
Free to compare
Why Your Premium Increased After You Turned 65
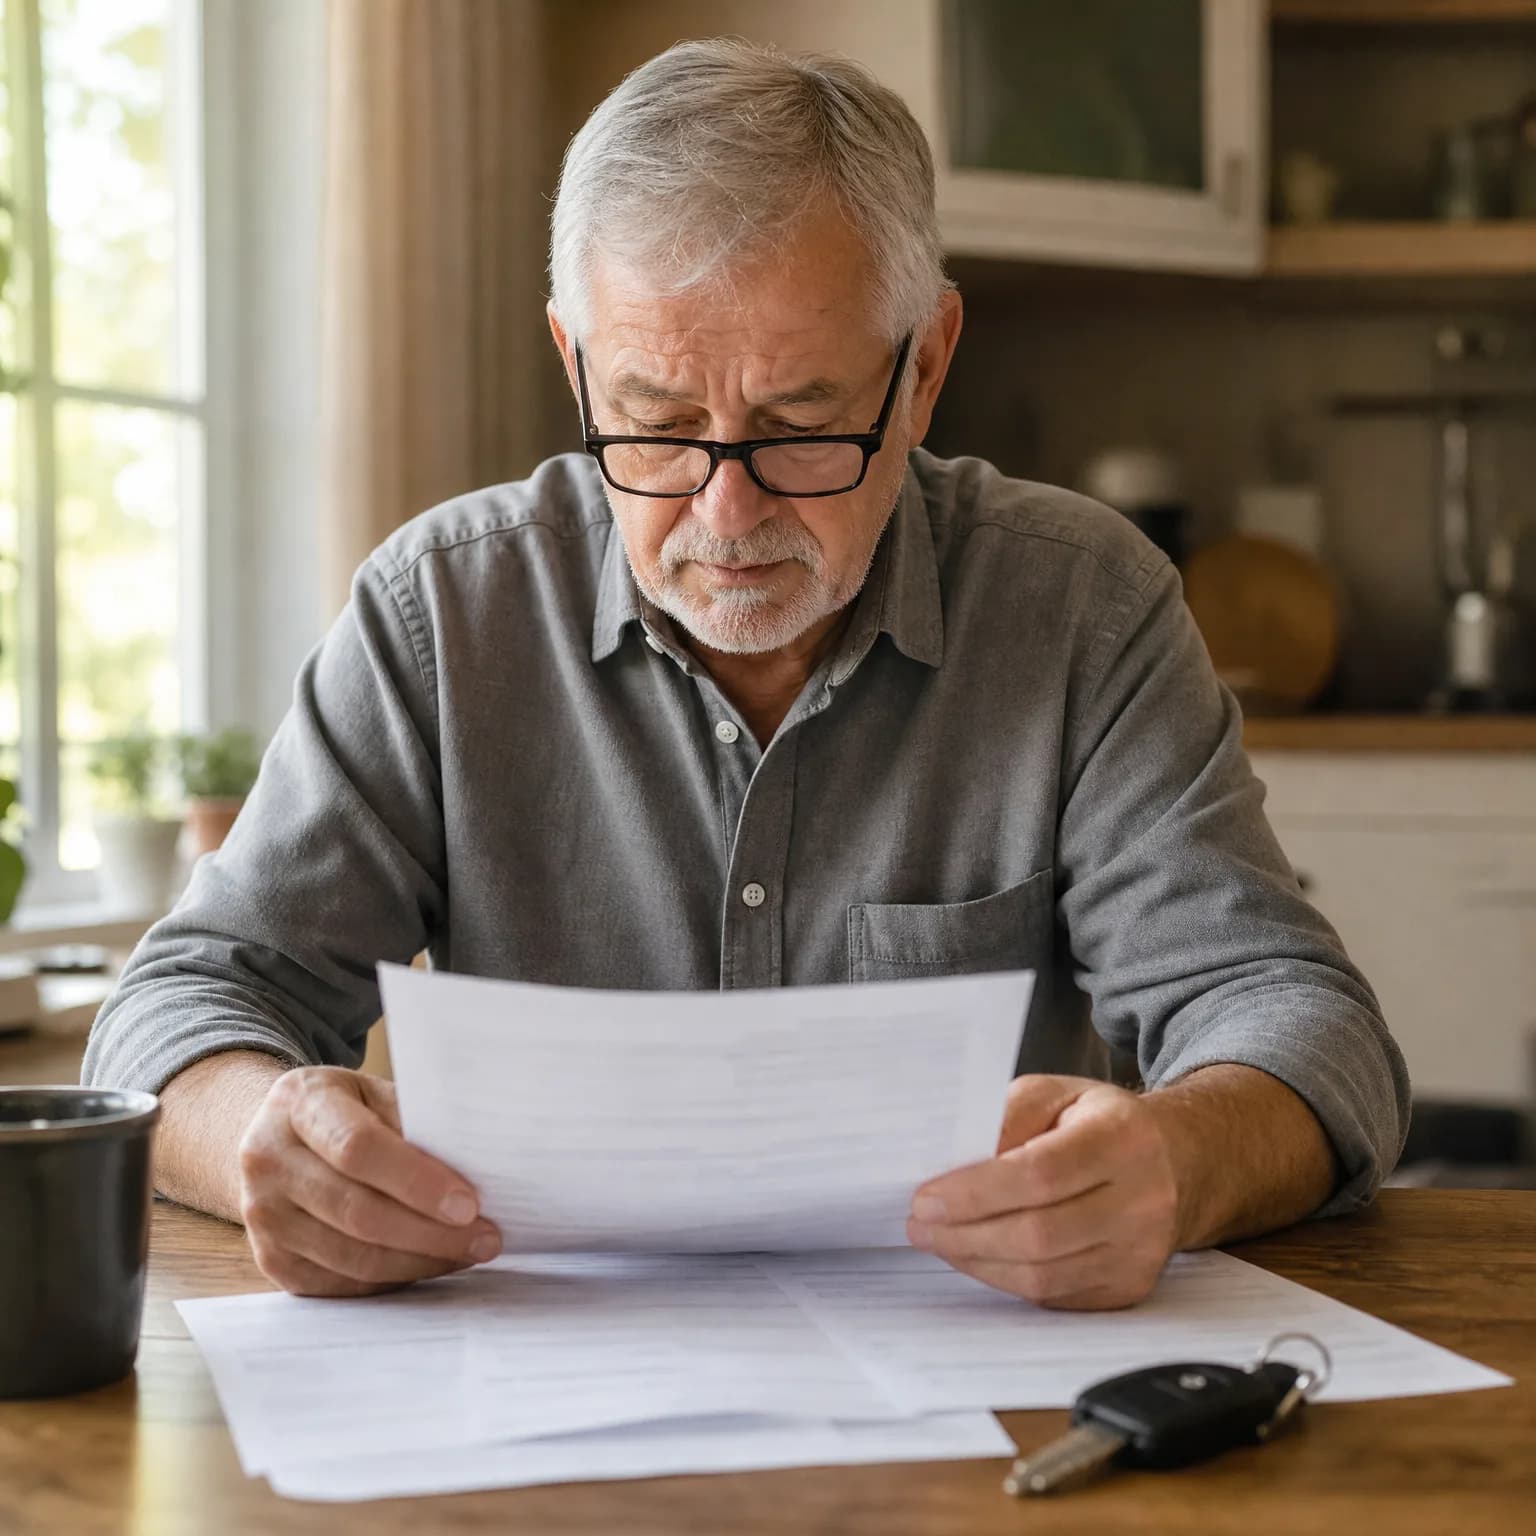
You opened your renewal notice expecting the mature-driver discount you heard about, and the premium went up instead. Your driving record is clean, your mileage dropped after retirement, and nothing about your coverage changed. The increase makes no sense until you understand how Massachusetts carriers handle the age-65 discount: they are required by law to offer it, but most will not apply it automatically.
Massachusetts General Laws Chapter 175 Section 113B requires insurers to establish rates for drivers aged 65 and older who otherwise qualify for the lowest rate classification at 25 percent less than the applicable classification rate. The statute creates a legal floor, not an automatic entitlement. Carriers satisfy the mandate by making the discount available, but the burden of confirming eligibility at renewal falls on you. If you never ask, you keep paying the higher rate.
“Massachusetts law requires the discount, but carriers will not apply it unless you confirm eligibility at renewal.”
Find Coverage Made for Drivers Over 65
Get My Senior Auto Insurance Quote25%
Massachusetts Senior Discount Floor
MGL c. 175 §113B requires insurers to offer rates for drivers 65 and older at 25% less than the applicable classification rate. The discount is age-based, not course-based, and applies to qualifying seniors who meet the lowest rate classification criteria.
MGL c. 175 §113B
How the Age-Based Discount Actually Works
The Massachusetts senior discount is age-triggered, not course-triggered. You do not need to complete a defensive driving course to qualify. The statute ties the discount to age 65 and to meeting the insurer's lowest rate classification, which typically means a clean driving record with no at-fault accidents or moving violations in the lookback period.
Most carriers define the lowest rate classification as zero surchargeable events under the Safe Driver Insurance Plan within the past six years. If you have an at-fault accident or a moving violation on your record, you may not qualify for the lowest classification until the event ages off. The discount applies only to the base rate, not to surcharges already applied under SDIP.
The 25 percent floor is a minimum. Some carriers exceed it in their filed rates, but they are not required to disclose by how much. The only way to know what your carrier actually applies is to ask your agent directly or compare quotes from carriers writing in Massachusetts.
The blocker: your carrier satisfied the legal mandate by making the discount available, but you never confirmed your eligibility at renewal, so the system kept charging the higher rate.
Carriers Writing Senior Policies in Massachusetts
Twelve major carriers write auto insurance in Massachusetts and all are subject to the age-65 discount mandate. Geico, Progressive, and National General operate in the standard tier and offer online quotes. State Farm and USAA operate in the preferred tier, which typically requires a cleaner driving record but may offer lower base rates before the discount is applied. Amica operates in the preferred tier and is known for senior-friendly underwriting.
Bristol West writes non-standard policies and requires broker access for quoting. If you have a recent at-fault accident or moving violation that disqualifies you from the lowest rate classification at standard carriers, a non-standard carrier may still offer competitive rates once the senior discount is applied. Compare at least three carriers to see how each applies the statutory floor to your specific profile.
Allstate, Farmers, Hartford, Liberty Mutual, and Travelers also write in Massachusetts. None of these carriers advertise their senior discount percentage publicly, so the only way to compare is to request quotes directly. When requesting quotes, confirm your age and ask the agent to verify that the age-65 discount has been applied before they finalize the premium.
12
Carriers Writing in Massachusetts
All twelve carriers operating in Massachusetts are required to offer the age-65 discount under state law. Tier, quote access, and base rate vary by carrier, but the statutory 25% floor applies to all.
Massachusetts Division of Insurance carrier filings

Coverage Adjustments That Make Sense at 65
Retirement changes your coverage needs in ways the standard policy does not account for. If you no longer commute, ask your carrier to reclassify your mileage. Most carriers offer a low-mileage discount for drivers under 7,500 miles per year, and some offer telematics programs that track actual mileage. The discount stacks with the age-65 discount and can reduce your premium by another 10 to 20 percent depending on the carrier.
If your vehicle is paid off and worth less than a few thousand dollars, dropping collision and comprehensive coverage may make financial sense. The rule of thumb: if the annual cost of full coverage exceeds 10 percent of the vehicle's current value, you are paying more in premiums than you would recover in a total-loss claim. Check your vehicle's actual cash value before making the decision, and keep liability limits high regardless of what you do with physical damage coverage.
Massachusetts requires personal injury protection as part of the compulsory coverage package. If you are enrolled in Medicare, PIP still applies as primary coverage for medical expenses after an accident, and Medicare coordinates as secondary. Do not drop PIP to save money; the coverage is mandatory and Medicare will not cover expenses PIP would have paid.
What Happens at Your Next Renewal
Once the discount is applied, it remains in effect as long as you continue to meet the lowest rate classification criteria. If you have an at-fault accident or receive a moving violation, the carrier will apply a SDIP surcharge at your next renewal, and you may lose eligibility for the lowest classification until the event ages off. The age-65 discount does not protect you from surcharges; it reduces the base rate before surcharges are applied.
Some carriers require you to re-confirm eligibility every renewal cycle. If your carrier sends an eligibility verification form with your renewal notice, return it immediately. Missing the deadline can result in the discount being removed, and you will need to re-apply to have it reinstated. Confirm with your agent whether your carrier requires annual re-verification or applies the discount continuously once eligibility is established.
Compare Carriers and Confirm the Discount
Request quotes from at least three carriers and ask each agent to confirm that the age-65 discount has been applied before they finalize the premium. Do not assume the discount is included just because you stated your age. Verify the discount line-item on the quote summary, and if it is missing, ask the agent to add it and re-quote. The statutory floor is 25 percent, but some carriers exceed it in their filed rates, and the only way to find out is to compare the final premium after the discount is applied.
Confirming Eligibility With Your Current Carrier
Call your agent or the carrier's customer service line and ask two specific questions: whether the age-65 discount has been applied to your current policy, and whether your driving record qualifies you for the lowest rate classification under their filing. If the discount is not applied, ask what documentation they need to verify your age and eligibility. Most carriers accept a driver's license copy or a signed attestation form.
If your carrier confirms you qualify but the discount is not reflected on your current policy, request a retroactive adjustment to your last renewal date. Some carriers will issue a credit; others will apply the discount going forward only. If the carrier refuses a retroactive adjustment and you have been eligible since age 65, document the conversation and file a complaint with the Massachusetts Division of Insurance. The statute does not permit carriers to withhold a mandated discount from a qualifying senior.
Get Your Free Quote
Get My Senior Auto Insurance QuoteFrequently Asked Questions
Does Massachusetts require car insurance companies to offer senior discounts?
Yes. Massachusetts General Laws Chapter 175 Section 113B requires insurers to establish rates for drivers aged 65 and older who qualify for the lowest rate classification at 25 percent less than the applicable classification rate. The discount is age-based and does not require completion of a defensive driving course.
Do I need to take a defensive driving course to get the senior discount in Massachusetts?
No. The Massachusetts senior discount is triggered by age 65, not by course completion. You must meet the insurer's lowest rate classification criteria, which typically means a clean driving record with no surchargeable events under the Safe Driver Insurance Plan in the past six years.
Will my car insurance automatically apply the senior discount when I turn 65?
Most carriers will not apply the discount automatically. You need to confirm your eligibility with your agent at renewal. If the discount is not applied and you qualify, request a retroactive adjustment to your last renewal date.
Can I lose the senior discount if I have an accident?
If you have an at-fault accident or receive a moving violation, the carrier will apply a SDIP surcharge at your next renewal, and you may lose eligibility for the lowest rate classification until the event ages off. The age-65 discount reduces the base rate before surcharges are applied, but it does not protect you from surcharges.
Which car insurance carriers in Massachusetts offer the best rates for seniors?
All twelve carriers writing in Massachusetts are required to offer the age-65 discount under state law. Geico, Progressive, State Farm, USAA, and Amica are commonly competitive for senior drivers, but the best rate depends on your specific profile. Compare quotes from at least three carriers and confirm the discount is applied before finalizing.
Should I drop full coverage on my car after I retire?
If your vehicle is paid off and worth less than a few thousand dollars, dropping collision and comprehensive may make sense. The rule of thumb: if the annual cost of full coverage exceeds 10 percent of the vehicle's current value, you are paying more in premiums than you would recover in a total-loss claim. Keep liability limits high regardless.
Does Medicare replace PIP coverage in Massachusetts?
No. Massachusetts requires personal injury protection as part of the compulsory coverage package. PIP applies as primary coverage for medical expenses after an accident, and Medicare coordinates as secondary. Do not drop PIP; the coverage is mandatory and Medicare will not cover expenses PIP would have paid.